

After a September that looked almost too good to last, a Goldman Sachs research note brought investors back to earth. Meta builds its own skilled-trades army with a $115 million job guarantee. Meta’s stock retreated roughly 4% on Friday, September 25, as the bank raised a pointed question about whether AI spending at this scale can ever generate sufficient returns.
The concern centers on Goldman Sachs estimates for the industry’s biggest AI spenders, known as hyperscalers. The bank projected those companies would collectively pour roughly $800 billion into chips and data centers in 2026 and approximately $1.1 trillion in 2027. Those are analyst projections, not company guidance.
The revenue math Goldman laid out is equally stark. Breaking even on that infrastructure may require approximately $300 billion in recurring annual AI-services revenue across the sector; generating strong profits could demand close to $1 trillion annually. These figures are analyst estimates, not Meta targets.
Meta’s own numbers illustrate the tension. Second-quarter capital expenditures ran to approximately $31.1 billion, while free cash flow compressed to roughly $784 million for the same period. Capital expenditure refers to money spent on physical assets such as servers and data-center buildings. For 2026, Meta has guided toward $130 billion to $145 billion in capital spending, nearly twice what it deployed in 2025.
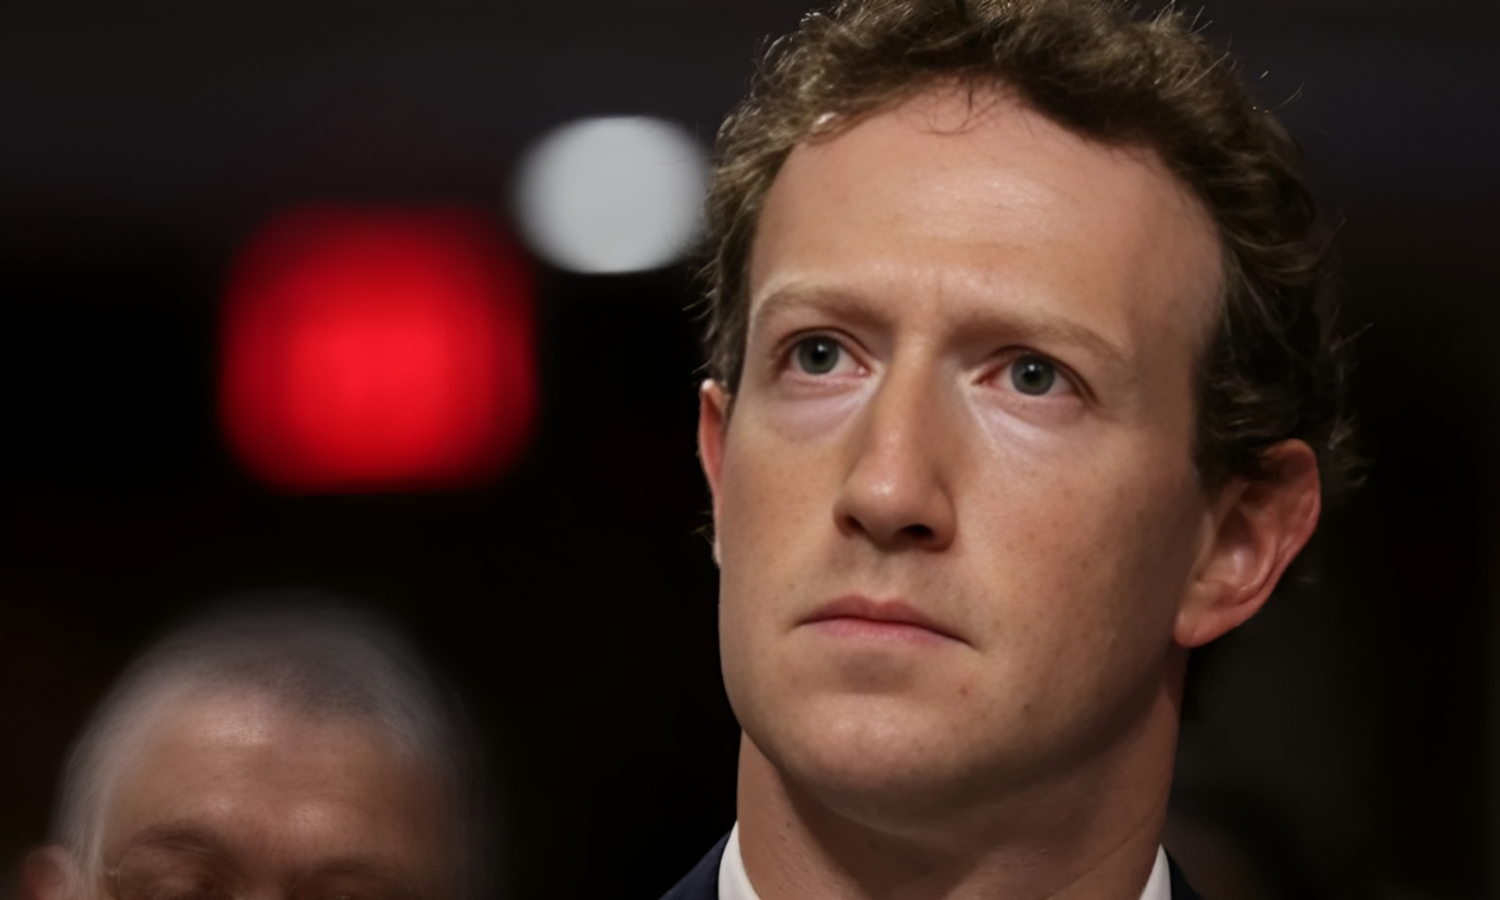
The share-price drop translated directly into a change in Zuckerberg’s estimated paper wealth, meaning the market value of his equity stake, not cash in an account. Forbes, as cited by Benzinga, reported the decline at nearly $9 billion, bringing his estimated net worth to roughly $257.5 billion. A separate prearranged plan to sell approximately 27,474 Class A shares, valued at roughly $21.36 million, was already on file under SEC Rule 10b5-1; it should not be read as a reaction to that day’s move, pending primary SEC filing confirmation.
The bear case is real, but it does not tell the whole story. Meta’s Advantage+ advertising suite, which uses AI to automate ad targeting and delivery, is operating at an annualized revenue run rate of approximately $75 billion. Its GEM ad-ranking system reportedly lifted Facebook ad clicks by 8.3% and conversions by 15.7% in early testing, suggesting certain AI investments are already producing measurable results in the core advertising business.
The selloff also carries important context. Meta shares had climbed approximately 36% during September alone, pushing the company close to a $2 trillion market valuation before the reversal. Broader pressure on expensive growth technology shares, driven partly by elevated Treasury yields, added to the pullback.
Meta’s upcoming earnings report, any revision to 2026 capital expenditure guidance, and free cash flow trends will tell investors whether this is a routine profit-taking correction or the start of a deeper reassessment of whether the AI infrastructure bet has a credible timeline to pay out.