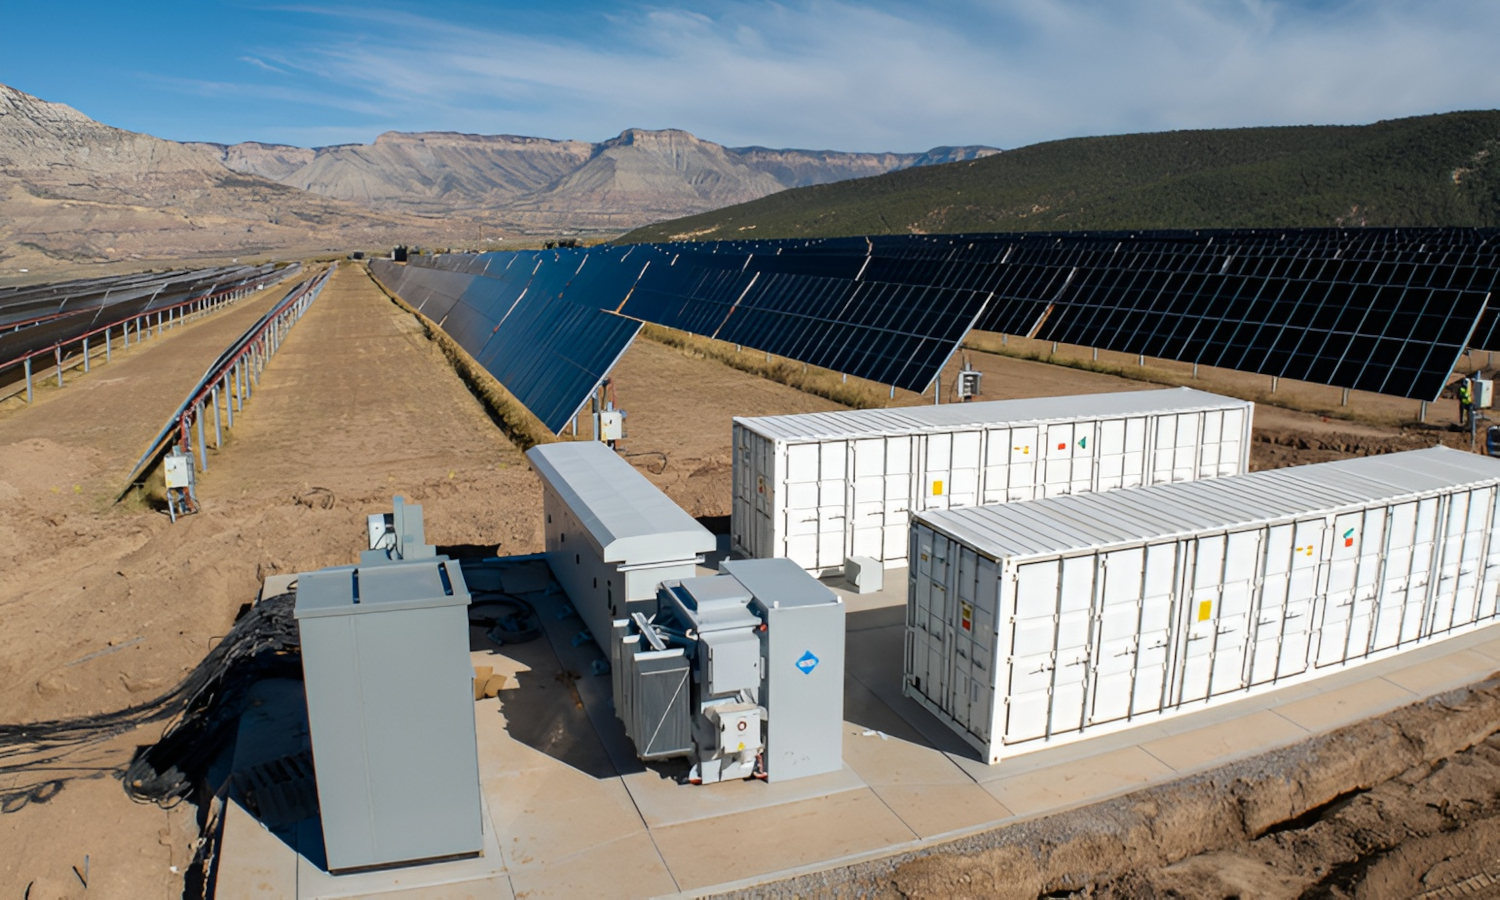
Battery storage has crossed a threshold that energy analysts have been watching for years. Wood Mackenzie’s latest levelized cost of electricity analysis finds that four-hour battery systems now undercut open-cycle gas turbines on modeled cost in all 43 global markets where both technologies were compared.
Falling battery prices driven by manufacturing scale, ongoing gas-turbine supply shortages, and fuel-price volatility have converged to eliminate the modeled cost advantage gas once held for peaking power. “Gas turbine shortages and rising fuel volatility are driving up peaking costs, while expanding battery manufacturing continues to push storage costs down,” said Ahmed Jameel Abdullah, a principal analyst at Wood Mackenzie responsible for the firm’s LCOE work across multiple global regions.
Storage is now joining solar on the competitive end of the generation cost curve. Single-axis-tracker solar already ranks as the lowest-cost new-build generation technology in 43 of 48 modeled markets, with onshore wind leading in the remaining five.
The Cost Divide Is Not Equal Everywhere
Regional economics vary sharply, and the gaps are getting wider, not narrower.
Middle East and Africa hold the world’s cheapest solar, with regional single-axis-tracker costs around $37/MWh in 2026. Four-hour storage in the region sits near $120/MWh in 2026, but Wood Mackenzie forecasts a 33% decline to roughly $80/MWh by 2035.
Saudi Arabia and the UAE are on track for solar costs below $20/MWh by 2033. Those figures make solar-plus-storage economics in the Gulf look less like an energy story and more like a real-estate story: location is almost everything.
China functions as the global benchmark for grid-scale storage costs, coming in more than 55% below the Asia Pacific regional average of approximately $134/MWh. Domestic supply-chain integration and manufacturing scale are identified as the main drivers of that gap.
Japan, Australia, and the Philippines remain expensive due to import duties, higher installation costs, and domestic-manufacturing policies. The cost spread across Asia Pacific is expected to widen further by 2030.
North American storage retains a cost advantage partly because tax credits offset some pressure from foreign-entity restrictions and supply-chain constraints. Near-term solar costs face headwinds from tariffs and antidumping actions, while Wood Mackenzie describes gas investment as entering a supply-deficit cycle through the late 2030s, driven partly by data-center electricity demand and constrained turbine availability.
Europe carries the highest fossil-fuel generation costs among all modeled regions. Battery capital expenditure rose roughly 2% in the latest update after cell prices rebounded about 10% from their 2025 low, though costs are forecast to decline 12% by 2031.
What LCOE Does Not Tell You
A cost crossover in a model is not the same as a solved grid.
Levelized cost of electricity measures lifetime modeled cost; it does not capture every requirement a grid operator must meet. Gas turbines can provide extended-duration output when fuel is available, while batteries are bounded by their state of charge, installed energy capacity, and recharge access.
The defensible conclusion from Wood Mackenzie’s analysis is that batteries hold a cost advantage for the four-hour peaking application, not that they replace gas under every operating condition. Tariffs, tax credits, local-content requirements, fuel subsidies, and capacity-market rules can strongly influence whether modeled advantages translate into actual projects.
If you are tracking energy investment or electricity prices, the number to watch is not the LCOE figure itself but the policy environment that either closes or widens the gap between what the model says and what gets built.