

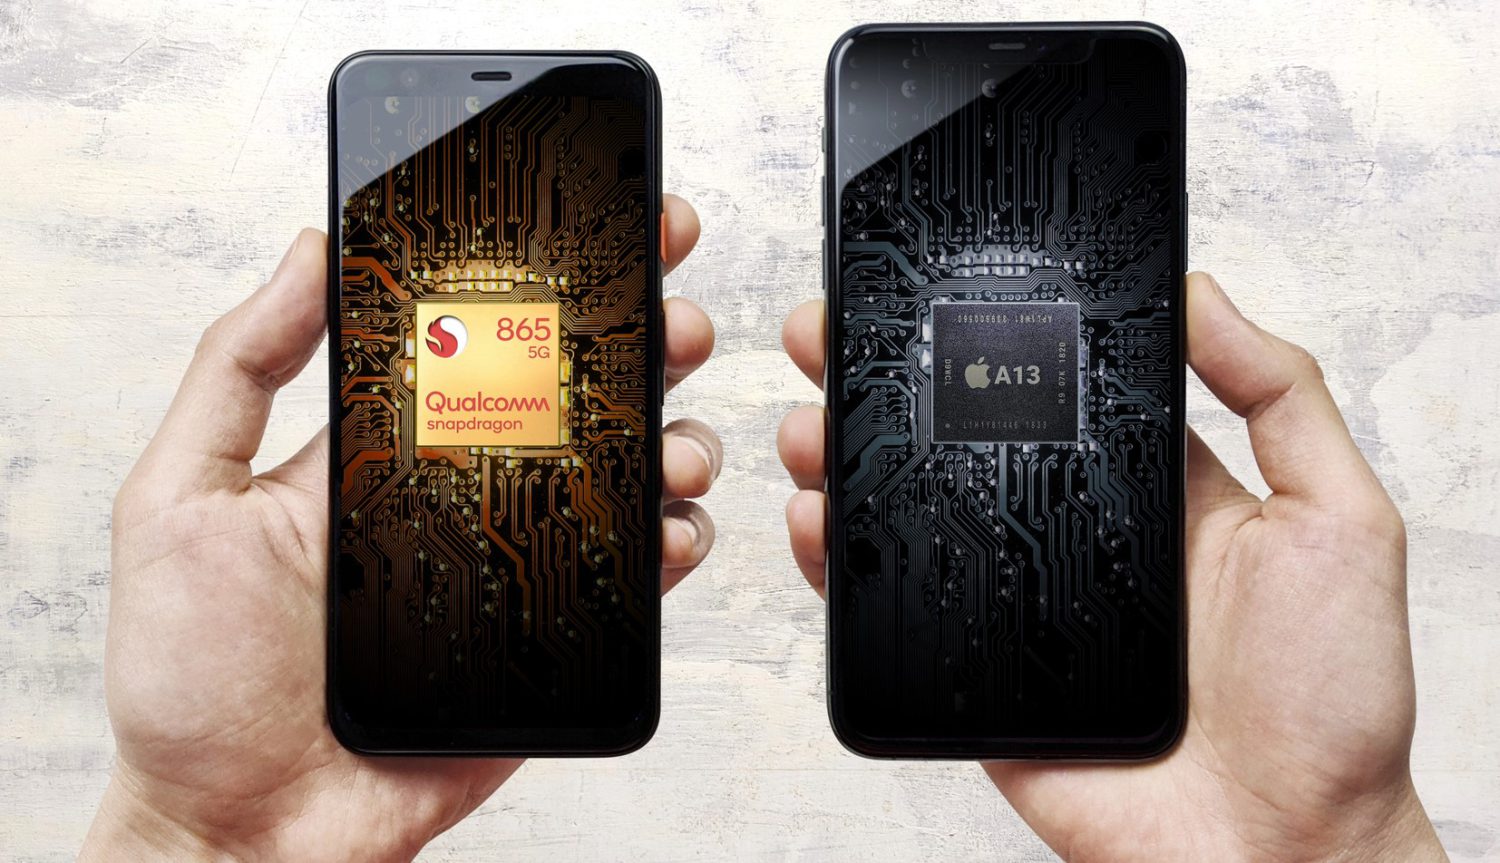
Apple is building its own custom silicon modem chips. Apple also just renewed its patent license with Qualcomm. Both things are true, and that tension is exactly what makes the September 24, 2026 announcement worth parsing carefully.
The renewal, effective April 1, 2027, confirms that Apple still needs access to Qualcomm’s wireless intellectual property even as it works to reduce its reliance on Qualcomm modem hardware. What it does not confirm is how much Apple will pay, how long the agreement runs, or whether the royalty economics changed at all. That silence splits the announcement into two very different stories depending on which part of Qualcomm’s business you are watching.
Two Businesses Inside One Deal
Qualcomm’s chip supply operation and its patent licensing arm are separate businesses, and this announcement only speaks to one of them.
Qualcomm operates two distinct revenue streams that are easy to conflate. One is its chip supply business, which sells modem hardware to device manufacturers including Apple. The other is Qualcomm Technology Licensing, known as QTL, which collects royalties from manufacturers that use Qualcomm’s cellular patents.
If you follow Qualcomm’s earnings, these two revenue streams matter very differently here. Apple renewing the patent license continues the licensing relationship, but it does not shield Qualcomm’s modem chip revenue.
According to Reuters, the renewed agreement extends Qualcomm’s licensing relationship with Apple even as Apple reduces its reliance on Qualcomm modem chips. MacRumors reported separately that Apple’s transition toward custom-designed modems is ongoing, though that reporting represents secondary coverage rather than an official Apple product disclosure.
The practical implication: Apple could reduce or phase down its Qualcomm modem purchases while remaining subject to a patent license. Whether it will, and at what rate, is a question this announcement does not answer.
What the Announcement Actually Says
Qualcomm confirmed a renewal date and nothing else.
The renewed agreement takes effect April 1, 2027. Qualcomm disclosed neither its duration nor its financial terms, according to the company’s official press release on PR Newswire and reporting from Yahoo Finance.
John Han, Qualcomm’s executive vice president and general manager of Qualcomm Technology Licensing, offered a single-sentence response in the company’s release: “We are pleased to extend the Apple license agreement.” The brevity of that statement is not incidental. It reflects exactly how much either company chose to reveal, which limits any precise forecast of what the renewal means for Qualcomm’s earnings.
The announcement confirms a future licensing relationship between the two companies. It does not establish whether Qualcomm negotiated favorable terms, unfavorable ones, or something in between.
The History Behind the Handshake
This is actually the second time these companies have found their way back to the table after a serious fight.
Qualcomm and Apple settled years of worldwide litigation in 2019. That settlement produced a six-year global patent-license agreement beginning April 1, 2019, along with a separate multiyear modem-supply arrangement, according to Reuters. The current agreement ran through March 31, 2027; the renewal follows the expiration of that existing term.
That history matters for a specific reason. The companies have already demonstrated they can fight bitterly, settle, and continue doing business. A second renewal does not guarantee harmony, but it does indicate that Qualcomm’s patent portfolio carries commercial weight with Apple.
The Unverified Numbers Behind the Bull Case
The licensing-versus-chips distinction has a logical foundation, but the financial figures attached to the bullish reading require independent confirmation.
Some analysts and investors interpret the renewal as evidence that Apple’s modem insourcing threatens Qualcomm’s chip revenue far more directly than its royalty revenue. That structural argument is defensible based on verified reporting.
Figures circulating in investor commentary were not independently verified against Qualcomm’s official filings in available sources. Those figures include specific QTL quarterly revenue and margin numbers, automotive growth rates, a reported BMW partnership, free cash flow totals, and valuation comparisons to Broadcom. Those numbers should be confirmed against Qualcomm’s Form 10-Q or official earnings release before being treated as established fact.
The specific financial case built around the structural argument requires primary-source confirmation before you treat it as settled.
The Risks the Renewal Does Not Remove
Undisclosed terms are the central limitation of any optimistic reading.
Without knowing the duration or royalty rate, it is not possible to determine from this announcement whether Qualcomm preserved its prior Apple-related royalty economics or accepted less favorable conditions. Apple’s modem transition also remains a concrete threat to Qualcomm’s component revenue, independent of whatever the patent agreement says.
Any argument that automotive, IoT, or data-center growth will offset declining handset revenue depends on margin comparisons, capital requirements, and execution timelines. This announcement does not address any of those factors.
What the Renewal Resolves, and What It Does Not
The announcement answers one narrow question and leaves the more consequential ones open.
The renewal confirms that Qualcomm’s wireless patent portfolio still holds enough commercial value that Apple agreed to continue licensing it rather than walk away. That is not nothing.
What the announcement does not tell you is how long the agreement runs or what Apple agreed to pay. The term, the economics, and the pace of Apple’s modem transition all remain open. So does whether Qualcomm’s diversification efforts can deliver at the margins required to replace lost chip revenue. Those answers will come from future earnings disclosures, not from a two-sentence press release.