Mitsubishi UFJ Financial Group plans to launch MUFG Emut Bank between January and March 2027, according to Japan Times reporting from November 4, 2026. The bank will not issue conventional ATM cash cards, making it the first institution connected to a major Japanese financial group to operate that way. Japan’s cash card dates to 1969, when the predecessor of Sumitomo Mitsui Banking Corp. introduced the country’s first version.
How Customers Will Get Their Cash
Withdrawing money requires four steps: unlock your phone, authenticate inside the Emut app, scan a QR code at a participating ATM, then enter your account PIN.
MUFG describes that sequence as more secure than a standard card-and-PIN combination, citing the growing sophistication of AI-assisted cyberattacks and phishing campaigns targeting bank customers. Each step adds an authentication layer that a stolen physical card alone cannot replicate.
App-Only Account Management
MUFG restricted Emut to smartphone access by design, arguing that limiting banking to a single authenticated device reduces exposure if customer data is compromised.
The security rationale holds only partially. QR-based authentication can reduce risks from card skimming and physical card theft, but it does not by itself neutralize phishing directed at the app, malware on the device, social engineering, or account takeover through credential theft. Losing a phone, facing a dead battery at an ATM, or hitting an app lockout each becomes a potential banking disruption under this model.
The ATM Network Behind the Cardless Promise
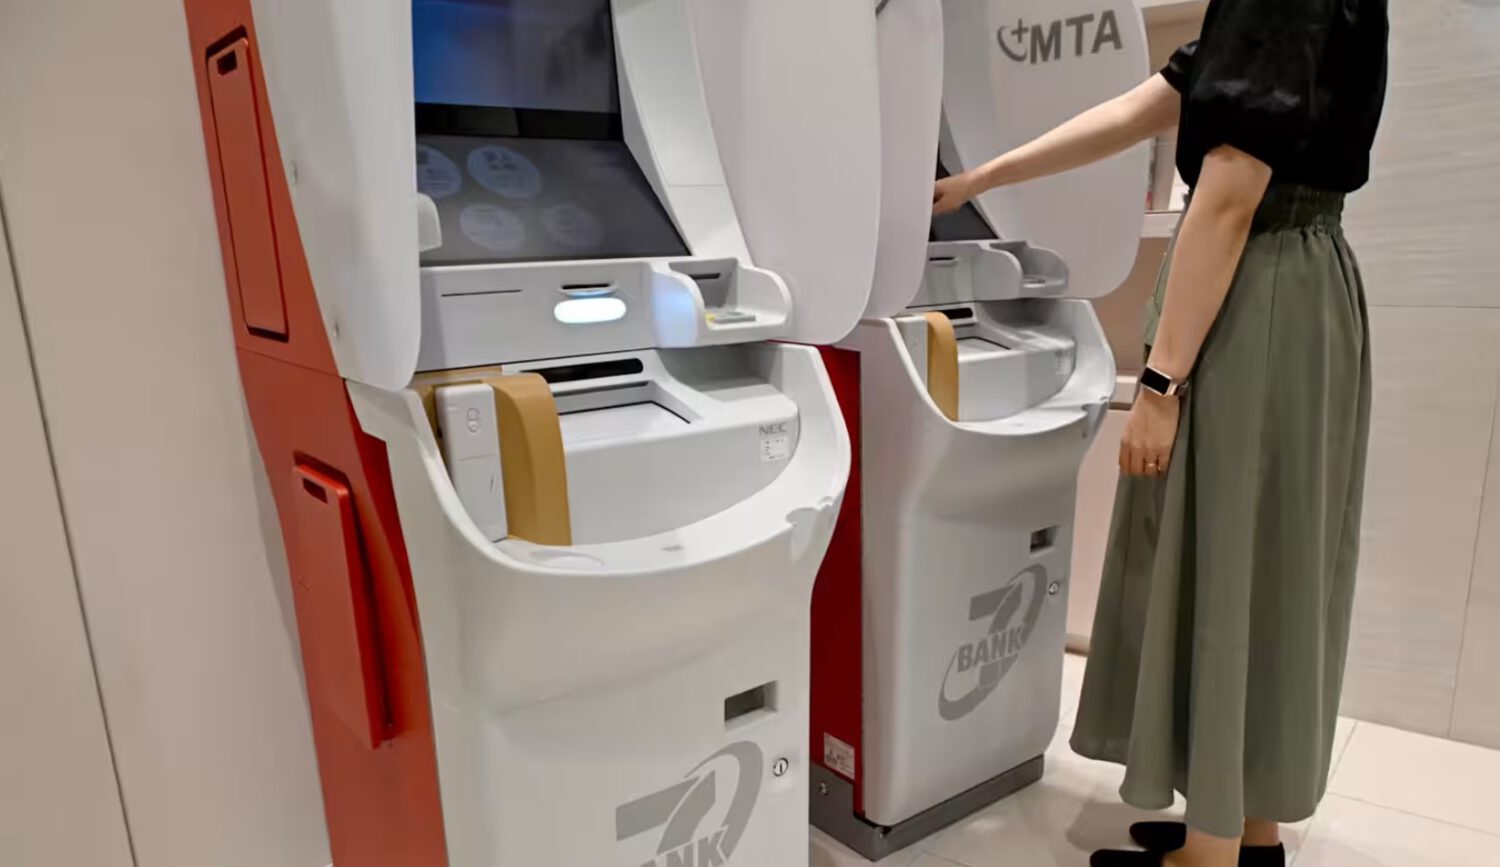
At launch, Emut customers are expected to access cash through approximately 29,000 Seven Bank ATMs nationwide.
Seven Bank is the financial-services arm of Seven & i Holdings, the company behind 7-Eleven in Japan. MUFG’s own branch ATMs will not be available to Emut customers at the start, though the bank may consider adding them later.
Cost Savings and Deposit Rates
Eliminating physical card production is expected to reduce operating costs, with MUFG aiming to redirect those savings toward services including deposit interest rates.
Rates on Emut accounts are expected to exceed MUFG Bank’s standard deposit rates, according to Japan Times reporting. Interest may be credited daily rather than on a twice-yearly schedule. Emut is also designed to offer payments and wealth management services, positioning it as a broader consumer finance product rather than a stripped-down digital account.
Limitations and Unconfirmed Details
Customers who cannot reliably maintain smartphone access may find Emut unsuitable, and several key product details remain unconfirmed ahead of the 2027 opening.
Customers without compatible smartphones, those with limited comfort using mobile apps, or anyone who cannot guarantee phone availability face real friction with this model. Exact deposit rates, eligibility conditions, fees, and procedures for lost or unavailable phones have not been confirmed publicly.
What It Means for Japanese Banking
If Emut attracts deposits and maintains dependable ATM coverage, it could pressure other large Japanese banks to test cardless models of their own.
The design does not eliminate cash. It changes the credential required to reach it, replacing a physical card with a smartphone-based identity and transaction authorization.