Search queries grew 12% year over year in Q3 2026, the fastest rate in five years. Search revenue also grew 12%, missed analyst estimates by roughly $1.6 billion, and sent Alphabet’s stock down approximately 10%.
The Numbers Behind the Selloff
Strong cloud results could not offset a Search miss and deeply negative free cash flow.
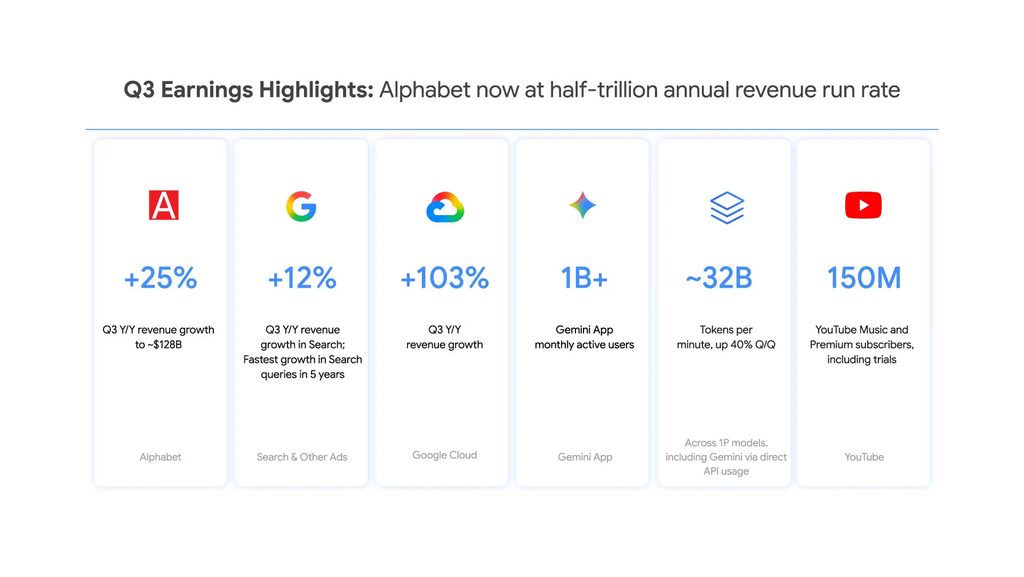
Alphabet reported Q3 revenue of approximately $127.6 billion, short of the $128.2 billion analysts expected, according to CNBC. Adjusted earnings per share came in at $2.67, well below the $3.02 consensus estimate.
Google Search and other advertising revenue rose to about $63.3 billion, up 12% year over year, but analysts had expected closer to $65 billion. Google Cloud was the clear bright spot, more than doubling to $30.7 billion against an estimate of $28.7 billion.
Free cash flow turned sharply negative at approximately $9.07 billion, versus an expected negative $2.70 billion. The deceleration in Search revenue drew additional attention from investors, with growth running at 19% in Q1, 17% in Q2, and 12% in Q3.
AI Mode Is the Structural Culprit
Conversational queries are longer and more frequent, but the ad infrastructure around them is still catching up.
Google Chief Business Officer Philipp Schindler acknowledged on the earnings call that strong growth in AI Mode queries directly affected Search performance because AI Mode carries lower monetization than conventional search. Alphabet separately identified foreign exchange as a significant contributor to the quarter-over-quarter deceleration, and the company has not disclosed exactly how much less revenue each AI Mode query currently generates.
AI Mode queries run three times longer than traditional searches. Globally, one in five uses voice, images, or documents, according to Google’s official blog.
Google says the majority of AI Mode queries are incremental, representing new activity rather than a replacement of existing searches. The company frames that growth as a future monetization opportunity.
The Fix Is More Ads Inside the Conversation
Multi-turn ads that evolve across a back-and-forth exchange are coming to the United States.
Expanding advertising into the AI experience itself is Alphabet’s stated response. AI Mode ads are moving into international markets, while the US will receive multi-turn ads capable of adapting across an extended AI dialogue, according to the earnings call.
Google is also scaling ads across AI Overviews and AI Mode to more users and more queries after early experiments it described as promising. The company’s research indicates users find AI Mode ads relevant, and early click-through rates on sponsored and organic product listings were reportedly similar, per 9to5Google citing Google research.
Whether advertisers will pay enough for conversational placements to match traditional Search economics remains an open question.
The Spending Commitment Investors Cannot Ignore
Fifty-one billion dollars in capital expenditures defined Q3 alone, and the bills ahead are larger still.
Alphabet maintained a full-year 2026 capex outlook of $195 billion to $205 billion and signaled that 2027 spending is expected to rise significantly and could exceed $300 billion, according to CNBC. That figure reflects a forward expectation rather than formal guidance.
Alphabet remains profitable, and Cloud’s strong quarter offers evidence that AI infrastructure can generate substantial revenue beyond consumer Search. The market’s concern is timing. Alphabet is committing enormous capital before AI Mode advertising has reached the yield of traditional Search, and how quickly that gap closes will determine whether Q3 reads as a transition quarter or the beginning of a longer squeeze.